

Money Eco: Budget / Expense
by Apponance, Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
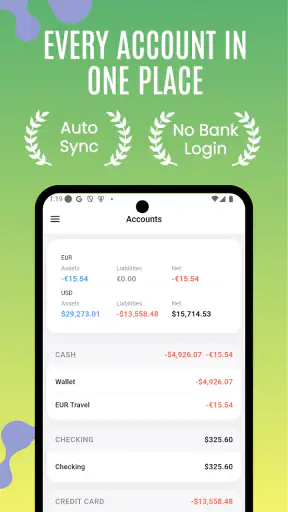
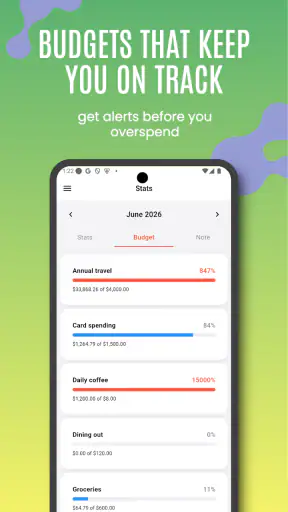
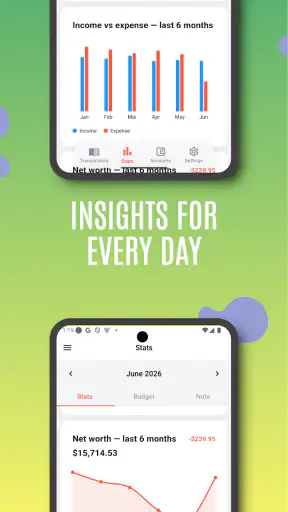
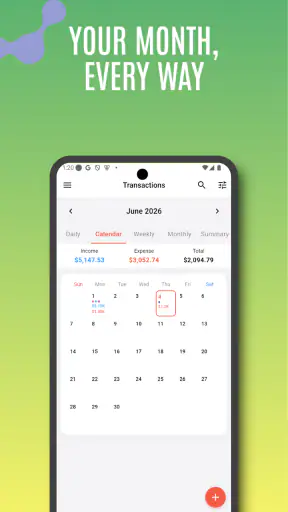
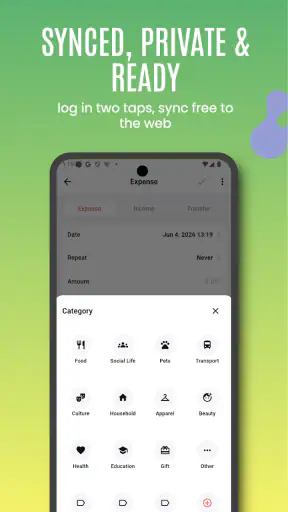
 Analysis by Getfullapps
I approached Money Eco: Budget / Expense as a practical finance app rather than a complete banking replacement. Its purpose is straightforward: help me record spending, organize a personal budget, and turn everyday money activity into visual reports that are easier to understand than a long list of transactions. That focus makes it appealing if you want more awareness of where your money goes without committing to a complicated financial-management system.
After using it, my impression is that Money Eco works best as a hands-on companion for people who are willing to enter and review their own information. It is not the kind of tool I would choose for someone who wants every bank account, card and bill synchronized automatically. For a person who prefers a simple record of expenses and a visual way to spot patterns, though, it offers a more approachable starting point than a spreadsheet.
How Money Eco feels in everyday use
The app sits in the personal finance category and is developed by Apponance, Inc. Its store summary emphasizes money management, budget tracking and financial visualization, and that description matches the way I would use it: I open it to capture an expense, check how a category is behaving, and decide whether the rest of the month needs a little more restraint.
The most useful habit is entering a purchase while it is still fresh. A coffee, a grocery run or a transport payment is much easier to classify immediately than to reconstruct several days later. That may sound obvious, but it is where many budget apps fail in practice. Money Eco only becomes useful when the record reflects real behavior, so I would treat quick entry as part of the routine rather than something to postpone until the weekend.
A realistic example is a person trying to reduce casual food spending. Instead of relying on memory, I would record each takeaway meal under the same category, then use the visual report to see whether the problem is one large purchase or a steady stream of small ones. The report is valuable not because it makes the decision for me, but because it turns a vague feeling—“I seem to be spending too much”—into something I can inspect and act on.
That visual approach is also helpful for users who find spreadsheets tiring. A spreadsheet can be more flexible, but it asks me to design categories, formulas and summaries before I can learn anything. Money Eco gives the process a more focused shape. The trade-off is that I have less freedom to build a completely custom financial model, which matters if I track investments, business reimbursements or complicated shared finances.
A good fit for deliberate tracking
I see the app as particularly suitable for students, first-time budgeters, couples who want a shared conversation about spending, and anyone trying to build a clearer monthly routine. It can also help someone who already knows the basics of budgeting but wants a lighter tool for daily expenses rather than a full financial dashboard.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The important word is deliberate. I would not install it expecting the app to fix disorganized finances automatically. Its value comes from the feedback loop between recording a transaction, reviewing the visual summary and changing a habit. If I only enter expenses occasionally, the charts can give me a false sense of precision because missing entries make any category comparison less trustworthy.
For that reason, I recommend choosing a small number of consistent categories at the beginning. Overly detailed labels may feel productive, but they create extra work and make it harder to compare one week with another. A simpler structure—such as food, transport, household, subscriptions and personal spending—usually gives a clearer first picture. I can always refine the system later if a category is hiding an important pattern.
What the current release tells me
The current version is 7.1.0, which suggests that the app has moved beyond an early first release and has had room to mature. It was released on July 18, 2022, and the present version is the one I would evaluate when deciding whether to make it part of a routine. I would still separate that evidence from expectations: a version number alone does not guarantee that every workflow will suit every user.
The app is free to install, with optional in-app purchases ranging from $0.99 to $14.99 per item. That makes it relatively easy to try without committing money at the start. I would nevertheless check which parts of the experience are available without payment before building a long-term system around it. A free entry point is useful, but the practical question is whether the reports and tracking tools I personally need remain comfortable to use over time.
Money Eco has an Everyone content rating and supports Android 7.0 or later. That broad compatibility is helpful for people using an older Android phone, especially if they do not want to replace a device simply to run a budgeting tool. The audience is not restricted to a narrow age group, although younger users should still understand that a chart is only as reliable as the information they enter.
The app has reached over ten thousand installs and holds a 4.7 average from 54 ratings, alongside 11 written reviews. Those figures indicate a positive early reception, but I would interpret them carefully rather than treating them as proof that it is the best choice for every financial situation. A smaller rating pool can reflect a focused audience, and personal finance needs vary widely between a single student and a household with several accounts.
How existing users may experience the evolution
For someone who has used Money Eco since an earlier version, moving to 7.1.0 is likely to feel less like learning an entirely different product and more like continuing with a tool that has had time to develop. I would expect the main appeal to remain the same: recording money activity and viewing it in a more understandable form. The safest practical approach is to update, review the existing categories and make sure the current workflow still matches the way you actually spend.
Before changing a long-standing budget routine, I would take a moment to look at the reports I depend on most. If a user has built a monthly habit around a particular category structure, consistency matters more than novelty. A new release can be welcome, but a budgeting system is only useful when the historical records and current entries remain easy to interpret together.
One of my preferred workflows is a two-pass review. I first enter expenses with minimal friction during the day. Later, perhaps at the end of the week, I check whether categories are being used consistently and look for one actionable pattern. This prevents the app from becoming a diary of purchases with no follow-through. It also avoids the opposite problem: spending too much time perfecting records instead of using them to make a decision.
Another useful technique is to compare intention with behavior. At the start of a month, I would decide which areas deserve attention, then use Money Eco’s visualization to see whether the actual pattern supports that intention. If transport spending rises because of a temporary event, I would not immediately create a permanent new rule. I would first decide whether the change is a one-off or a recurring habit. The app can show the pattern, but judgment still belongs to me.
Where it is stronger than familiar alternatives
Compared with a notebook, Money Eco makes it easier to turn a collection of entries into a visual overview. A notebook can feel personal and flexible, but it requires manual totals and offers little protection against arithmetic mistakes. Compared with a spreadsheet, the app is more focused and less intimidating for someone who does not want to design formulas. That simplicity is its main strength.
It also has an advantage over an overly elaborate financial platform when my goal is simply to understand spending. Large finance services can be useful when automatic account connections, investment tracking or bill management are essential. They can also introduce more setup, more screens and more financial information than I need. Money Eco makes more sense when I want a dedicated expense-tracking space rather than an all-in-one financial command center.
There is a trade-off here that is easy to miss. Manual entry gives me control over what gets recorded and how categories are defined, but it also creates responsibility. An automatic system may save time, while Money Eco’s approach can encourage me to notice each purchase. For users who learn best by actively engaging with their spending, that extra step is not merely a burden; it can be part of the benefit.
I would choose a different option if automatic synchronization is non-negotiable, if I need detailed investment analysis, or if my finances depend on business accounting and tax-ready records. I would also look elsewhere if several people need simultaneous access to a sophisticated shared household budget. Money Eco’s focused design is more convincing for personal awareness than for complex financial administration.
Small habits that make the reports more useful
The first practical tip is to decide how I will treat refunds before I start. If a returned purchase is recorded inconsistently, a category can look healthier or worse than it really is. I would use one repeatable method for purchases, refunds and transfers, then keep that method throughout the month. Consistency matters more than choosing a theoretically perfect system.
The second is to separate review time from entry time. Entering a transaction is a capture task; interpreting the report is a planning task. Combining both every time can make small purchases feel tedious, while never reviewing the report turns the app into storage. A short weekly check is a better compromise for many people: correct obvious category mistakes, identify the largest pressure point and choose one change for the following week.
The third is to use visual information to ask better questions instead of chasing a perfect score. If one category dominates, I would ask whether it is necessary, seasonal, shared or simply misclassified. If several categories look small individually but large together, I would consider whether a broader discretionary group would reveal the real issue. The point is not to make the chart attractive; it is to make the next decision clearer.
A fourth insight is to avoid changing categories in the middle of a comparison unless there is a good reason. If I rename or split categories every few days, the report becomes difficult to read and historical patterns lose meaning. I would begin with a stable structure, observe it for a full budgeting cycle and only then decide whether a change would genuinely improve the information.
Friction points worth considering
The biggest limitation is the dependence on user discipline. Someone who wants passive monitoring may find manual tracking tiring, especially when purchases are frequent or spread across several payment methods. The app can encourage awareness, but it cannot know about an expense I never record. That makes the quality of the result uneven for users whose routines are already overloaded.
There is also a risk of focusing too much on visual presentation. A colorful or convenient report can make finance feel more approachable, but it does not automatically explain why spending changed or what should happen next. I would use the visualizations as prompts for reflection, not as a substitute for checking balances, upcoming obligations or other financial details outside the app.
The free model is another point to evaluate personally. Since optional purchases are available, I would begin with the free experience and test the exact workflow I expect to use: adding entries, organizing them and reading the reports. If a paid item becomes necessary for the feature that makes the app worthwhile to me, I would compare that cost with the time saved and the clarity gained rather than paying simply because I had already entered data.
Privacy-minded users may also want to think carefully about their comfort level before recording sensitive financial details in any finance app. I would avoid entering information that is not needed for my budgeting purpose, and I would use a sensible device lock. Good personal-finance habits include limiting unnecessary detail, not just categorizing every transaction perfectly.
Who should try it, and who should skip it
I would recommend Money Eco to a person who wants a free starting point for budget and expense tracking, prefers visual summaries and is comfortable taking an active role in recording purchases. It is especially attractive if a spreadsheet feels too technical but a full banking platform feels excessive. The broad age rating and older Android support also make it approachable for a wide range of Android users.
I would skip it in favor of a more specialized alternative if I needed automatic bank feeds, advanced forecasting, investment portfolios, formal accounting or a highly collaborative household setup. I would also skip it if I know that manual entry will last only a few days. In that case, the best app is not necessarily the one with the nicest report; it is the one whose input method I will actually maintain.
For existing users, my advice is to treat the current release as a reason to review the routine, not to rebuild everything automatically. Keep categories that still reflect real life, remove unnecessary complexity and check a few recent entries for consistency. For new users, start small: track the expenses that matter most, establish a repeatable naming system and use the first reports to find one behavior worth changing.
What I would watch next
When judging Money Eco over a longer period, I would pay attention to whether the app continues to make repeated entry and review feel effortless. In a finance tool, small points of friction matter because they appear every day. I would also watch how clearly the app helps users move from a visual report to an action, since understanding a pattern is only half of budgeting.
I would keep an eye on how the experience serves both new and returning users as the version develops. Existing records should remain understandable, while newcomers should be able to create a useful system without a long setup process. Those two needs can conflict: more flexibility may help experienced users but overwhelm beginners. The best evolution would preserve the approachable core while giving careful trackers more control where it genuinely helps.
My final view is positive but measured. Money Eco is not a replacement for a bank, accountant or comprehensive financial platform. It is a focused tool for turning personal spending into a record I can review and a visual pattern I can act on. The app’s free entry point, current 7.1.0 release and strong average among its ratings make it worth trying, but its real success depends on whether I can maintain the habit of entering information.
My recommendation is simple: try it if you want a clearer picture of everyday spending and are willing to participate in the process. Start with a few stable categories, review the reports regularly and judge the app by whether it changes a decision—not merely by whether it displays attractive summaries. For that specific purpose, Money Eco: Budget / Expense is a sensible, approachable option.
Pros
- Simple interface makes daily expense tracking quick and approachable.
- Useful budget categories help organize spending more clearly.
- Income and expense records can reveal recurring spending patterns.
- Suitable for users who want a focused personal finance tool.
- Fast entry process encourages consistent financial tracking.
Cons
- Some advanced planning tools may be limited compared with full finance suites.
- Manual transaction entry can become tedious for frequent purchases.
- Budget accuracy depends on keeping every expense updated.
- The app may feel basic for users managing investments or multiple accounts.
- Data export and sharing options may not meet every user’s needs.
FAQs for Money Eco: Budget / Expense
What is Money Eco: Budget / Expense used for?
Money Eco: Budget / Expense is designed to help you organize your personal finances in one place. You can record income and spending, categorize transactions, review where your money goes, and follow your budget over time. After testing the app, its main appeal is its straightforward approach: it focuses on everyday expense tracking rather than trying to replace a full banking service or investment platform.
Is Money Eco: Budget / Expense suitable for beginners?
Yes, the app is generally suitable for beginners who want a simple way to start managing their money. The basic workflow is easy to understand: create or select a category, enter the amount, and save the transaction. Users who have never maintained a budget may still need a little time to decide how to organize categories and spending limits, but the interface is less intimidating than many advanced finance applications.
Can I use Money Eco: Budget / Expense without connecting my bank account?
Money Eco: Budget / Expense is primarily useful as a manual budgeting and expense-recording tool, so you can track finances without giving the app direct access to your bank account. This can be reassuring for users who prefer privacy and control. However, manual entry requires consistency: if you forget to record purchases or income, the reports and remaining-budget figures may not accurately reflect your real financial situation.
Does Money Eco: Budget / Expense protect my financial information?
Before using any personal finance app, you should review its current privacy policy, permissions, and data-handling practices in the official store listing. Since budgeting apps may contain sensitive information about income, purchases, and financial habits, avoid entering unnecessary banking credentials or highly confidential details unless the app clearly explains how they are protected. Also use a secure device lock and keep the application updated.
Is Money Eco: Budget / Expense free, and are there any limitations?
The availability of free features, advertising, premium tools, or in-app purchases can vary by platform and may change with future updates. The free version is typically enough for trying basic income and expense tracking, but some advanced options may require payment depending on the current release. Check the Google Play or App Store page before downloading to confirm pricing, subscriptions, supported devices, and cancellation conditions.

Money Eco: Budget / Expense
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via admin@apponance.com, visit https://apponance.com, or review their https://www.apponance.com/privacy.html.










